Yalla’s new strategy is gaining traction, with rising game revenue and paying users offsetting weakness in its core voice-chat business.
By Doug Young
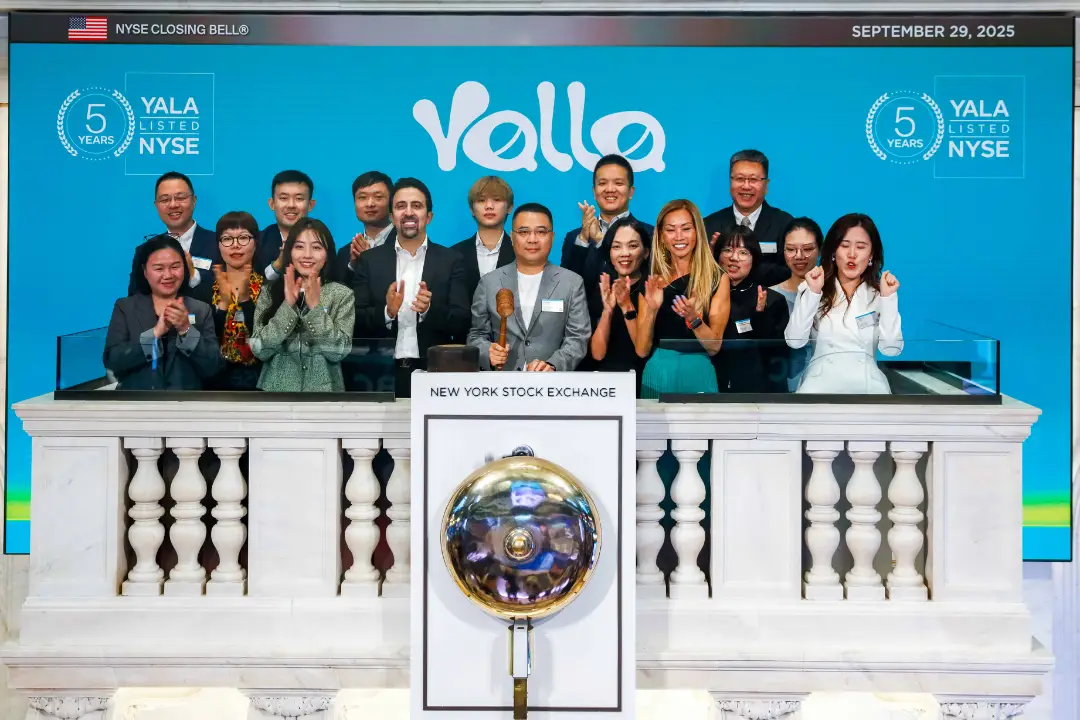
Yalla Group (YALA.US) returned to revenue growth in the third quarter as its push into more sophisticated mobile games began to deliver results, helping offset declining income from its established voice-chat services.
The Middle Eastern social media and gaming company reported revenue of $90.4 million for the three months ended September, up 0.9% year on year. Gaming revenue rose 13.7% to $38.4 million, accelerating from 11.6% growth in the previous quarter. The company also recorded its first increase in paying users in almost two years.
Yalla expects growth to strengthen through the end of 2026 and return to double digits next year. But expanding its gaming business will require higher investment in research and development and marketing, potentially putting pressure on margins in the near term.
The company held $772.2 million in cash and short-term deposits at the end of September, compared with $754.6 million at the end of 2025, giving it substantial resources to fund the expansion.
Founder, chairman and CEO Yang Tao described gaming as the company’s top strategic priority for 2027, saying its latest initiatives were beginning to contribute to revenue and diversify its growth drivers.
Gaming offsets weakness in core business
Voice-chat services remain Yalla’s largest revenue source, accounting for 56% of third-quarter revenue, which stood at $90.4 million. However, revenue from the business declined year on year and accounted for a lower percentage of the total as the newer gaming operations gained ground.
The number of paying users increased 6.2% from a year earlier to 12.1 million, the first year-on-year rise in the metric since the fourth quarter of 2024. The increase suggests Yalla’s move towards more committed gamers is beginning to broaden its paying customer base.
The company forecast fourth-quarter revenue of $83 million to $90 million. At the upper end of the range, that would represent growth of 7.2% from the $83.9 million recorded in the same period last year.
Yalla initially benefited from limited competition in the Middle East and North Africa social media market, delivering rapid growth through its voice-chat platforms and associated casual games. As the market matured and competitors expanded, growth slowed, prompting the company to reposition itself around more substantial gaming products.
New titles target international markets
Yalla’s gaming strategy combines internally developed titles with distribution partnerships involving external developers.
Its first major initiative was a desert-themed strategy simulation game (SLG) launched in April. The company upgraded its graphics and gameplay during the third quarter and plans a broader marketing campaign for the revised version in the fourth quarter.
It also launched an ocean-themed SLG in September through a partnership with a developer whose team includes veterans of established strategy-game studios. Yalla is responsible for global distribution, targeting markets including North America, Europe and the Middle East.
The game generated more than $2 million in gross billings for Yalla in October, its first full month following launch on Google Play and Apple’s App Store.
Yang said the early performance was encouraging and that the company would continue investing in marketing and user acquisition to support the title’s growth.
Three analysts surveyed by Yahoo Finance forecast Yalla’s revenue will increase approximately 12% next year to $383 million, from an estimated $342 million in 2026.
Higher investment weighs on earnings
The expansion comes with rising costs. Third-quarter net income fell to $32.7 million from $40.7 million a year earlier, reflecting increased spending on research and development and marketing. Despite the decline, Yalla maintained a net margin of 36.2%, while its non-GAAP net margin reached 41.5%.
Management said it would seek to balance investment in new games with tighter cost controls. The company plans to reduce user-acquisition spending on products that have yet to demonstrate meaningful revenue or returns, reallocating resources to projects with stronger prospects.
Yalla shares rose 4.4% following the results. The stock trades at approximately 7.1 times earnings, broadly in line with midsized gaming companies such as IGG (0799.HK) and Zengame (2660.HK). By comparison, Tencent (0700.HK) trades at about 13 times earnings and NetEase (9999.HK) at 17 times.
The success of Yalla’s gaming expansion could support a higher valuation, although the company will need to demonstrate that its new titles can sustain growth and generate returns as investment increases.
Source:
Bamboo Works
To subscribe to Bamboo Works free weekly newsletter, click here